
Illustrative Case: London Sweep → NY Expansion

Single-day example; not representative of average behavior. Click image for detailed view.
Key Findings
- Liquidity raids cluster around session transitions. Intraday activity peaks at the London open and the London–NY overlap, reaching ~2× the daily average M1 tick volume (EURUSD, 2019–2026).
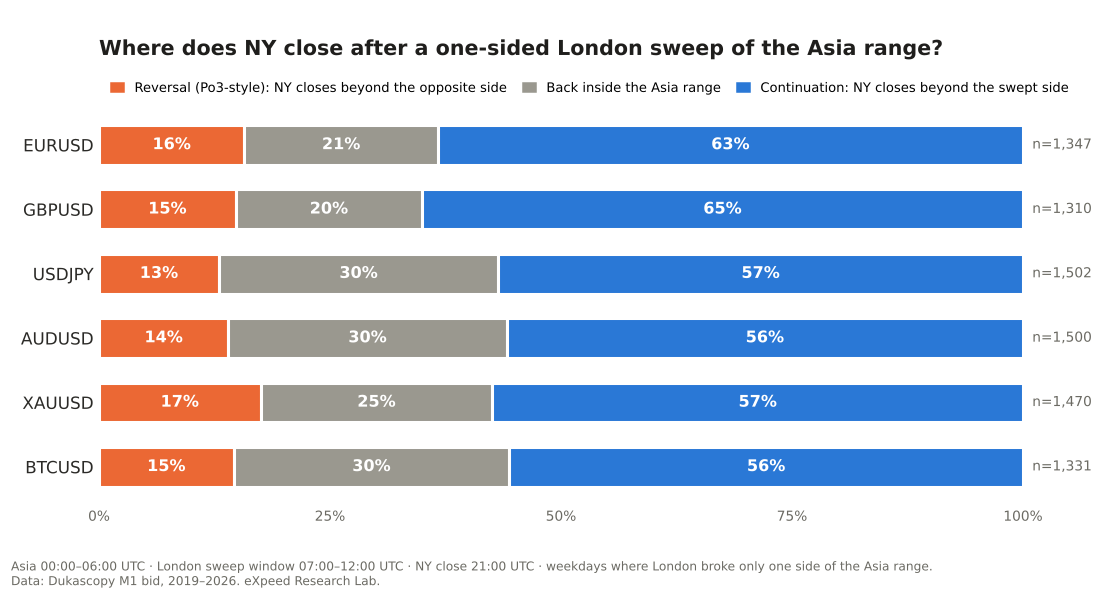
- London sweeps are near-universal, but follow-through is modest. By midday London, price has broken the Asia range on ~97% of days, largely explained by the session volatility cycle. After the first break, NY direction is statistically indistinguishable from a coin flip for major FX pairs, while full Po3-style reversals occur on only 13–17% of one-sided sweep days.
- Asia range size influences volatility distribution. Days in the widest Asia-range quintile see 1.26–1.57× normal London–NY ranges across six instruments, robust to prior-day volatility. Narrow Asia ranges do not precede abnormally large expansions in absolute terms.
Data: Dukascopy M1, 2019–2026 (EURUSD, GBPUSD, USDJPY, AUDUSD, XAUUSD, BTCUSD). Updated October 2026.
Our Research Framework
A structural model describing liquidity accumulation, sweep events, and displacement cycles across major sessions.

Click image for detailed view
- Session Liquidity : Price consolidation during low-volatility sessions where resting liquidity accumulates.
- External MSS : Structural shift occurring after external liquidity is swept.
- First FVG : The first fair value gap formed immediately after displacement.
Current Research Topics
External MSS Research
Statistical analysis of market structure shifts after liquidity sweeps.
First FVG Behavior
Study of displacement-generated imbalance patterns.
London Raid Model
Quantitative study of liquidity sweeps during London session.
Latest Publications
Recent quantitative studies on session liquidity behavior and displacement events across major FX pairs.
- 2025 — Asia Range Statistical Study (EURUSD / GBPUSD)
- 2025 — London Raid Probability Model
- 2024 — NY Displacement Behavior
Working Paper Series
About the Research Lab
The eXpeed Research Lab focuses on quantitative analysis of liquidity behavior and market structure events across global financial markets. Our research examines how liquidity accumulates, is swept, and leads to displacement events across major trading sessions such as Asia, London and New York markets.